Harry Dennis · Mortgage Advisor · San Diego

The right mortgage begins with understanding you.

Buying, refinancing, or investing? Harry explains the numbers, compares the tradeoffs, and gives you a clear strategy for the next move.

Mortgage Advisor with C2 Financial Corporation

PurchaseRefinanceInvestmentVA & FHA

Harry Dennis NMLS #46163 · CA DRE #01273034
C2 Financial Corporation NMLS #135622 · CA DRE #01821025

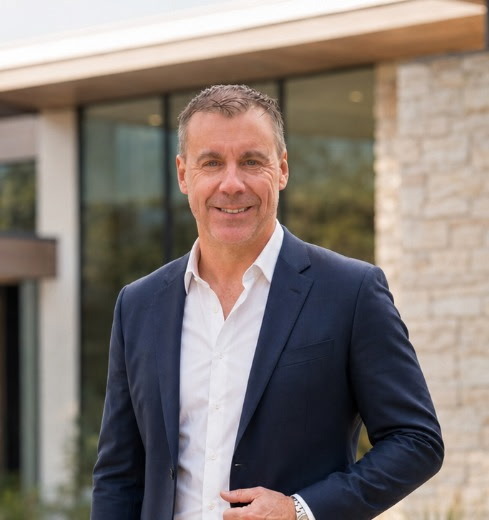
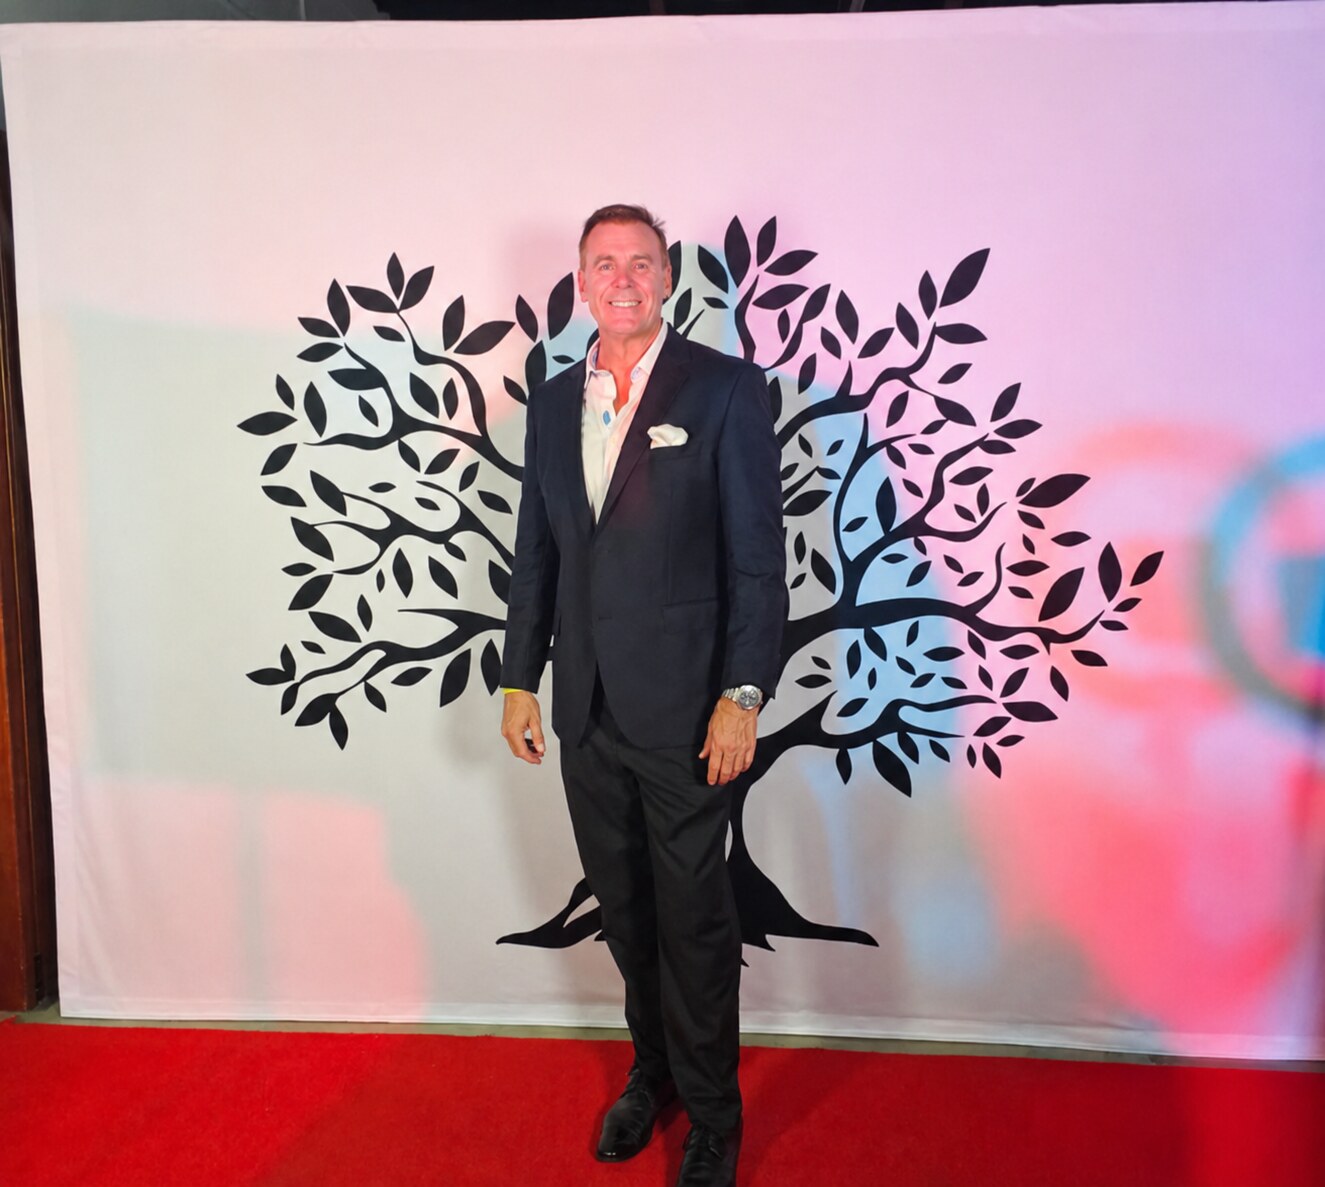
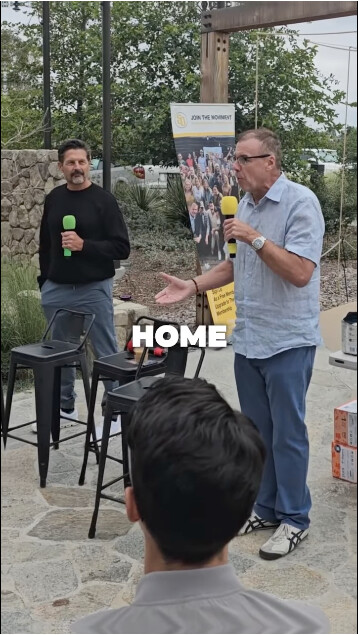
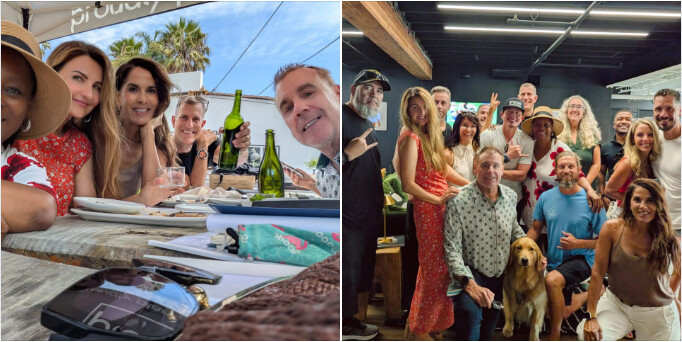
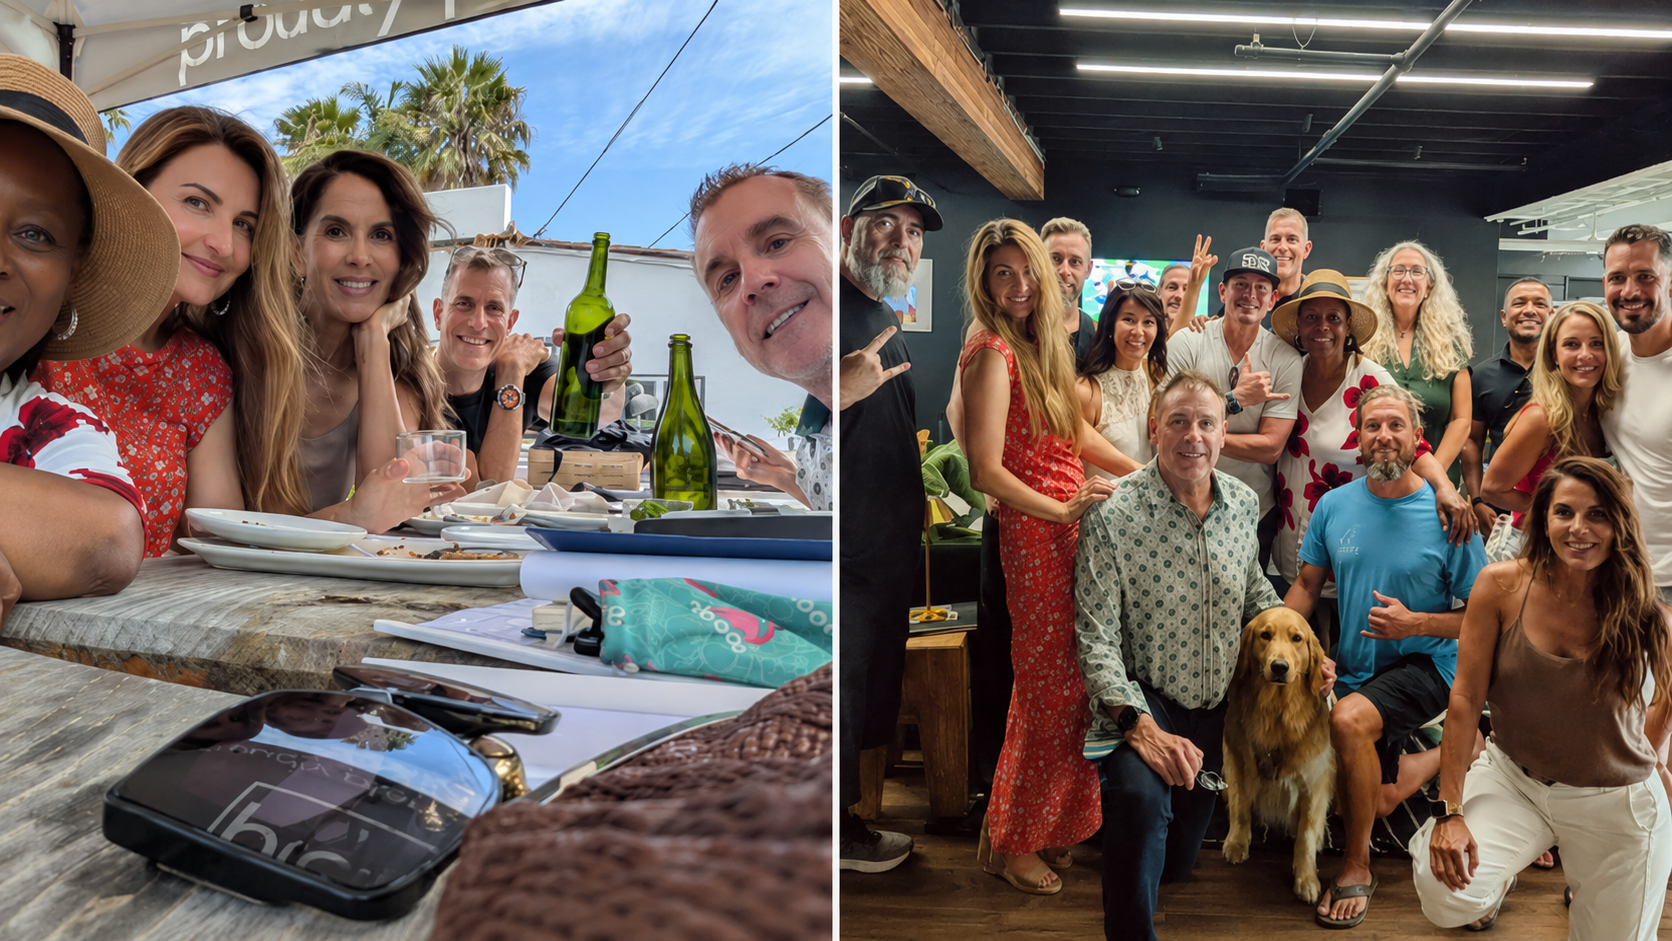
Harry Dennis, San Diego mortgage advisorHarry Dennis at a San Diego business eventHarry Dennis speaking at a community gathering
Your San Diego mortgage advisorHarry DennisC2 Financial Corporation · Harry NMLS #46163Tell Harry what you are planning →
Explore your options ↓
People firstUnderstand the person
Education firstSimplify the complicated
Strategy firstLook beyond the rate
Relationships firstThink beyond the transaction

People + numbers

Your goals first.
Your loan second.

Rate is only one variable. Harry looks at payment, cost, cash flow, liquidity, equity, timing, risk and family goals—then explains the tradeoffs in plain language. Open any card for a quick overview.

01

First-time buyers

Map out purchasing power, cash-to-close, and potential assistance programs.

What does this mean?

There is not one universal first-time-buyer program. Depending on eligibility, buyers may use conventional, FHA, VA, USDA, state, or local options.

  • Assistance may help with a down payment or closing costs.
  • Income, credit, location, occupancy, and education rules vary by program.
  • Availability and funding can change, so current eligibility must be checked.
02

VA & FHA

Review eligibility, down-payment requirements, and property considerations.

How are they different?

VA-backed loans

For eligible Veterans, service members, and certain surviving spouses. A Certificate of Eligibility and lender approval are required. Eligible borrowers may have a no-down-payment option and no monthly mortgage insurance; a funding fee may apply.

FHA-insured loans

Made by approved lenders and insured by FHA. They may allow a lower down payment and more flexible qualification, but mortgage insurance, loan limits, and property requirements apply. FHA is not limited to first-time buyers.

03

Self-employed

Explore bank-statement and alternative-documentation programs when appropriate.

What will a lender review?

Self-employed borrowers can qualify, but lenders generally need to verify that income is stable and likely to continue.

  • Documents may include personal or business tax returns, business records, and a profit-and-loss statement.
  • How income is calculated depends on the business, ownership share, loan program, and lender.
  • Bank-statement or other alternative-documentation loans are program-specific and may have different costs or requirements.
04

Jumbo & investors

Compare financing for larger balances, investment properties, and complex goals.

What do these terms mean?

Jumbo

A jumbo loan is above the current conforming loan limit for its location and property type. Because it falls outside standard Fannie Mae or Freddie Mac limits, qualification, reserves, and pricing can vary by lender.

Investment property

This generally means a home that will not be your primary residence. A lender may review your finances, reserves, property use, and allowable rental income. Requirements differ by program.

05

Refinancing

Evaluate the full cost and benefit before changing rate, term, payment, or equity.

When can it make sense?

Refinancing replaces an existing mortgage with a new loan. It may change the rate, term, monthly payment, or provide access to equity—but it usually involves closing costs and a new approval.

  • Compare the new payment with upfront costs and total interest.
  • A lower payment can come from extending the repayment period.
  • Consider how long you expect to keep the loan and when savings may outweigh costs.

Not sure where you fit?

Start with the real numbers and the real goal.

Talk with Harry

General education only. Loan availability, terms, costs, property standards, and eligibility depend on the borrower, lender, program, and current rules. This page is not a commitment to lend or a determination of qualification.

The mortgage quarterback

You should not have to become the mortgage expert.

Harry coordinates the borrower, Realtor, processor, underwriter, appraiser, title, escrow, insurance and lender—so the team keeps moving toward the goal.

Start with a conversation →
  1. 1

    Understand the person

    Start with your goals, timeline, concerns, family plans and complete financial picture.

  2. 2

    Explain the numbers

    Translate income, debt, reserves, cash flow and equity into something useful.

  3. 3

    Compare the tradeoffs

    Review appropriate options beyond today’s rate or payment, including cost, liquidity and risk.

  4. 4

    Navigate the next step

    Give a clear recommendation, coordinate the field and communicate before surprises happen.

A mortgage strategy built around your future
Buying today→Building equity→Your next move→Long-term financial goals→A legacy for your family

Harry helps you consider how today’s mortgage decision may affect your finances, flexibility, and future plans—not just your next monthly payment.

Run the numbers

Estimate the monthly payment.

Change the assumptions to see how price, down payment, rate, taxes, insurance and HOA dues affect the estimate.

Estimated monthly payment

$0

Principal & interest$0

Property tax$0

Insurance$0

HOA dues$0

Estimated loan amount$0

Educational estimate only. It does not include mortgage insurance, closing costs, points or every loan-specific charge.

Review the estimate with Harry

Mortgage questions, plain answers

Know what the words mean before you sign.

These are the questions buyers ask most often. Open any answer for a clear starting point, then ask Harry how it applies to your income, property, timeline, and goals.

Ask Harry a question
01How much home can I comfortably afford?

Start with the monthly housing payment that fits your real budget—not only the largest loan you may qualify for. Include principal, interest, property taxes, homeowners insurance, possible mortgage insurance, HOA dues, maintenance, and room for other priorities. Harry can help translate that comfortable payment into a realistic price range.

02What is a debt-to-income ratio?

Your debt-to-income ratio, or DTI, is your total monthly debt payments divided by your gross monthly income. Lenders use it as one measure of your ability to manage a new payment. Acceptable limits vary by lender, loan program, and the strength of the rest of your application.

03How does my credit affect a mortgage?

Your credit report and credit scores can affect both approval and pricing. In general, stronger credit may create access to more choices and lower rates, but credit is not the only factor. Before applying, review your reports, keep payments current, and ask before opening new credit or making a large financed purchase.

04Do I really need 20% down?

No. Some conventional and government-backed programs may allow a smaller down payment for eligible borrowers. A lower down payment can preserve cash, but it may increase the loan amount, monthly payment, and mortgage-insurance cost. The useful question is which tradeoff best supports your full plan.

05Is a 15-year or 30-year mortgage better?

A 15-year loan generally has a higher monthly payment but builds equity faster and usually costs less total interest. A 30-year loan generally lowers the required monthly payment and offers more cash-flow flexibility, but usually costs more interest over time. “Better” depends on your budget, reserves, other goals, and how long you expect to keep the loan.

06Fixed rate or adjustable rate—which should I consider?

With a fixed-rate mortgage, the interest rate does not change during the loan term. An adjustable-rate mortgage, or ARM, may begin with a fixed period and then change based on its index, margin, and caps. An ARM can fit some timelines, but you should be comfortable with the maximum possible payment—not only the starting rate.

07What is the difference between prequalification and preapproval?

Both can estimate what a lender may be willing to lend, but lenders use the terms differently and may review different levels of information. Neither is a guaranteed loan offer. Ask what documents, credit review, and underwriting work were completed so you know how much weight the letter carries.

08What is the difference between the interest rate and APR?

The interest rate is the cost charged for borrowing the principal. APR is a broader annualized measure that includes the interest rate plus certain points, broker fees, and other loan charges. APR can help compare similar loans, but it is not the same as your interest rate or monthly payment.

09What are closing costs and cash to close?

Closing costs can include lender and third-party fees, prepaid interest, taxes, insurance, and initial escrow deposits. Cash to close also accounts for your down payment, deposits already paid, credits, and other adjustments. Your Loan Estimate provides an early breakdown; your Closing Disclosure provides the final terms and costs before closing.

10What is a balloon payment?

A balloon payment is a large lump-sum payment due at the end of a loan after smaller regular payments have not fully paid off the balance. It may require a sale, refinance, or substantial cash payment. Because refinancing is never guaranteed, understand the amount, due date, and alternatives before accepting this feature.

11Is it better to rent or buy?

Neither choice is automatically better. Renting can offer flexibility and fewer repair responsibilities. Buying may fit when you expect to stay for several years, can comfortably handle the full payment and upkeep, and have enough cash for closing costs and reserves. Compare total monthly costs, moving plans, maintenance, insurance, taxes, and the risk that home values can change—not just rent versus principal and interest.

General education only. Guidelines and loan terms vary. Consumer references: CFPB mortgage answers · CFPB rent-or-buy considerations · Freddie Mac loan comparison

Harry in conversation

Hear it directly from Harry.

Business-focused videos on preparation, loan choices, affordability, and the decisions that shape a successful purchase.

YouTube · Long-form conversation

LEARNin Lending LIVE with Harry Dennis

Local lending questions, market context, credit, and practical home-finance guidance—played here without sending visitors into a social feed.

Do buyers really need 20% down?

Harry explains why 20% down is not the only path for every qualified buyer.

What buyers should know about FHA loans

A focused look at down payment, mortgage insurance, and the larger loan picture.

A smoother mortgage process starts early

Why getting organized before finding the perfect home can make the process easier.

These players are limited to the selected business videos. Harry’s full social profiles remain available in the About section for visitors who intentionally want to explore them.

The person behind the numbers

People + numbers. That’s the whole idea.

Harry Dennis is a San Diego mortgage advisor and financial educator who helps people make complex home-financing decisions easier to understand.

Raised in Annapolis, Maryland, Harry studied accounting at the University of Maryland and began his career with a foundation in financial statements, tax returns, cash flow, assets and liabilities. After moving west, he found a natural fit in mortgages: a field where people, numbers, problem-solving, real estate and relationships come together.

With approximately 25 years of mortgage-industry experience, Harry brings calm to the process and keeps each recommendation connected to the client’s lifestyle, family and long-term goals.

Harry NMLS #46163CA DRE #01273034
C2 Financial CorporationNMLS #135622 · CA DRE #01821025

Professional foundation

Financial fluency. Mortgage experience. Human judgment.

Harry’s background helps him look beyond a rate quote. He connects the documents, the cash flow, the property, and the person—then makes the tradeoffs easier to understand.

01

More than two decades in mortgages

Experience across purchase, refinance, first-time buyer, investment, second-home, jumbo, FHA, VA, and self-employed borrower scenarios.

02

Business + accounting education

A Business/Accounting degree from the University of Maryland, supported by an early-career foundation in public accounting in the Maryland, D.C., and Annapolis area.

03

Comfort with complex financials

Experience reading financial statements, cash flow, profit-and-loss statements, balance sheets, and business tax returns for multiple entity types.

04

A broker’s range of options

Access to a broad lending network allows Harry to compare programs and structures, subject to each lender’s current guidelines and borrower eligibility.

Harry’s working methodListen. Analyze. Educate. Advise.
EthicsHonestyCommunicationEducationIntegritySimplicityLeadershipCommunity

Professional profile information supplied by Harry Dennis for this concept and subject to final approval.

Beyond the transaction

Community, mentorship, and the next generation.

From first-time buyer classes and lending livestreams to networking events and veteran homeownership conversations, Harry brings education into the community.

PitchFest 2025“Empower people to follow their passion and achieve what they really want in life.”

PitchFest reflects the larger goal behind The Group: connection, practical business planning and mentorship that help people use opportunity well and grow with purpose.

Harry Dennis with San Diego professionals in OceansideOceanside · San Diego County
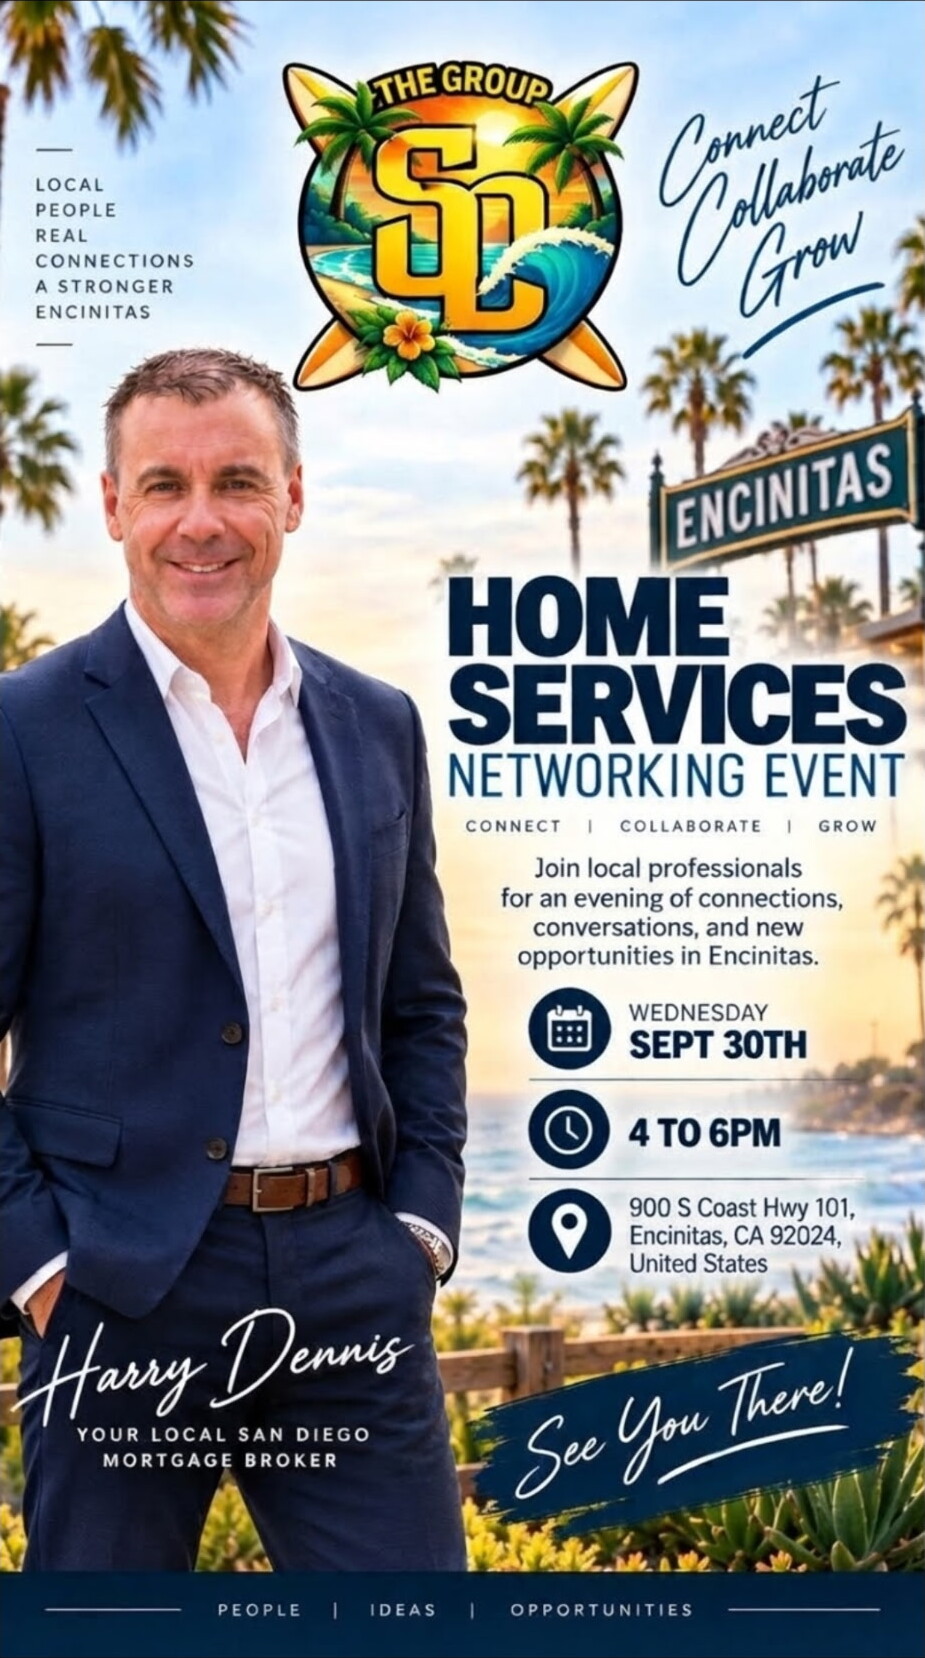
Home Services Networking Event with Harry Dennis and The Group SD in Encinitas on September 30, 2026
C2 Financial CorporationHarry Dennis NMLS #46163 · CA DRE #01273034
C2 NMLS #135622 · CA DRE #01821025

Upcoming in Encinitas

Home Services Networking Event

Connect with local home-service professionals for an evening of conversations, relationships, and new opportunities in Encinitas.

DateWednesday, September 30, 2026
Time4:00–6:00 PM
Location900 S Coast Hwy 101
Encinitas, CA 92024

Life beyond the work

Family keeps the work personal.

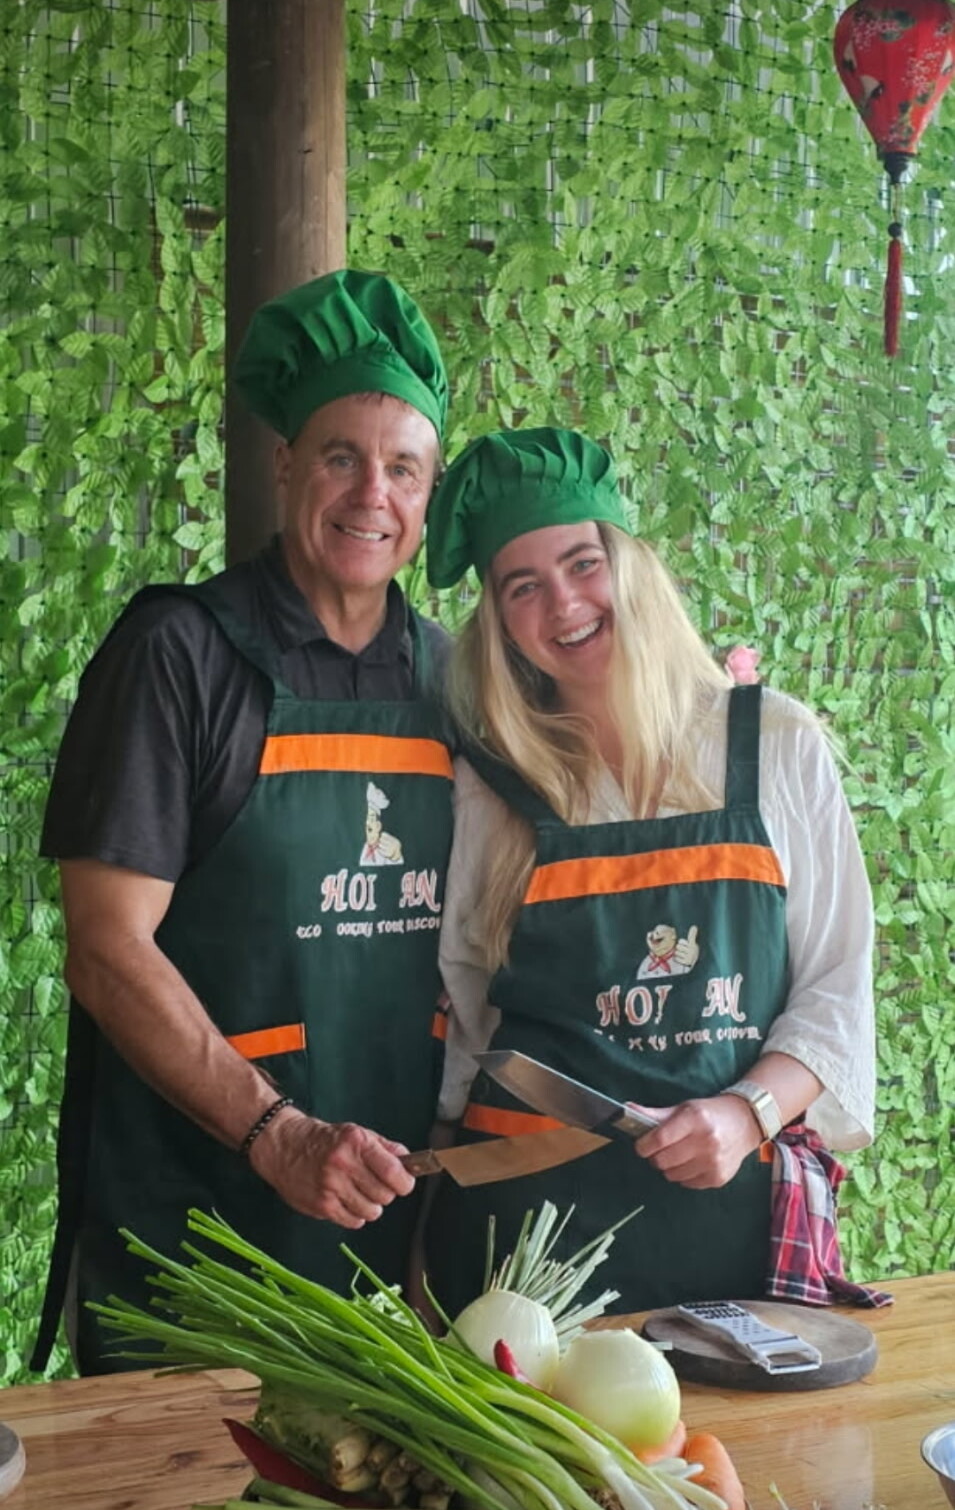
Harry is a father of three—Hope, Hudson, and Harrison—and family time is where he recharges. Whether traveling, cooking, running, doing yoga, getting outside, or relaxing with Willy, his golden retriever, those relationships keep the idea of “home” grounded in real life.

Home is more than a transaction. It is where the people you care about build their lives.

A clear next step

Tell Harry what you are planning.

Harry Dennis, San Diego mortgage advisor

Choose your goal and timeline. The site will prepare a message in your email or text app for you to review and send.

Your message is not stored on this website. Your device will open the selected app, where you press Send.